The deductible
The policy deductible affects the owner share independently of the repair scope. A roofing request does not create a deductible waiver or establish what the insurer will pay.
Understand where roof findings end and policy decisions begin after damage.
Damage, repair scope and insurance payment are related questions with different answers. The inspection addresses roof condition; the insurer decides coverage under the policy.
This guide explains the common moving parts so the roofing conversation can stay clear without promising a claim outcome.
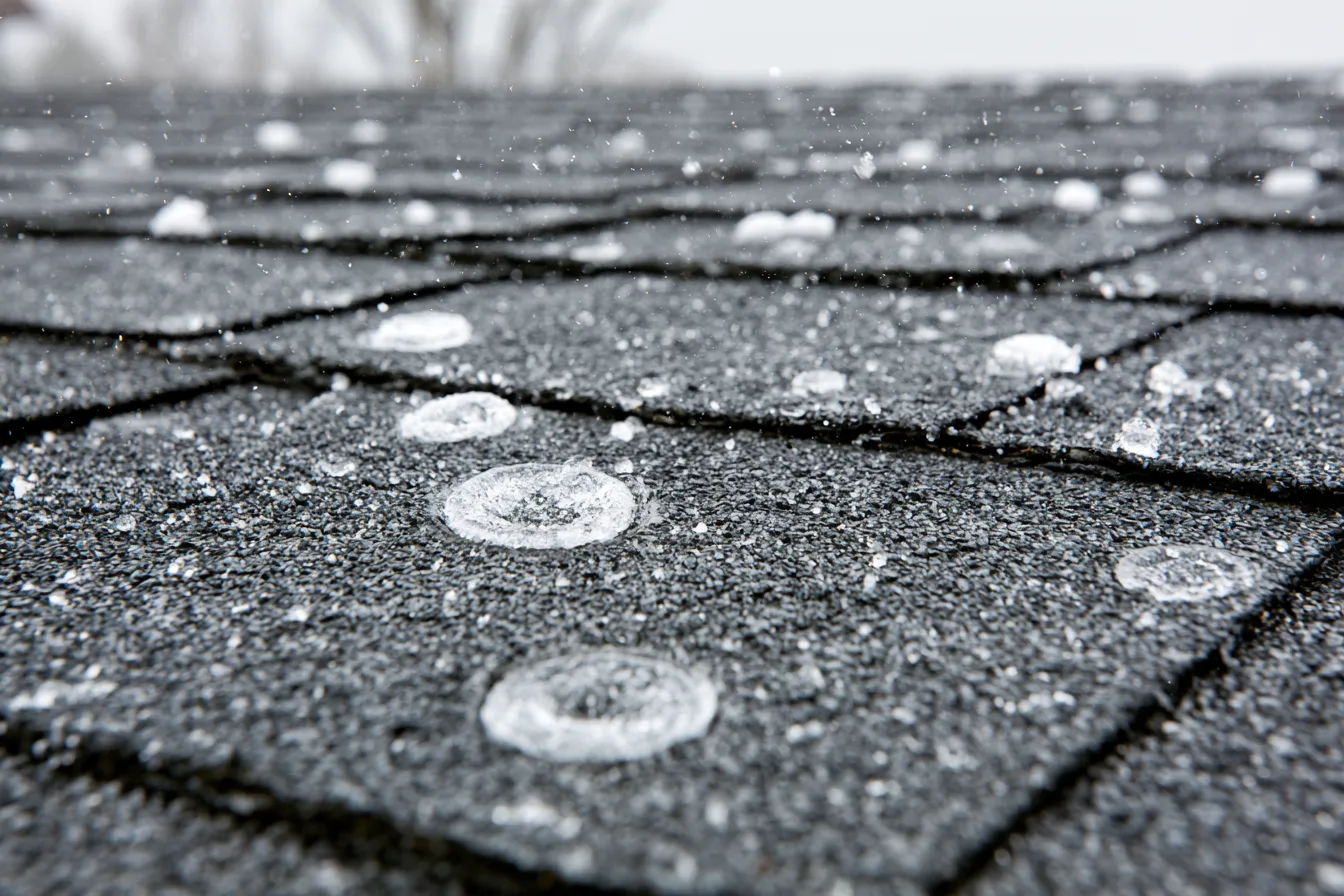
The roof assessment identifies observed damage and the work needed. Photos, dates and the property history can inform a claim, but nearby storm reports do not prove damage at one address.
The insurer applies policy terms, exclusions and deductibles to the reported loss. A roofer can explain the roof work; that does not establish claim representation or guarantee a payment.
The storm and hail roof service explains the physical assessment and repair options.
The policy deductible affects the owner share independently of the repair scope. A roofing request does not create a deductible waiver or establish what the insurer will pay.
Some policies calculate an initial payment with depreciation withheld and allow recovery after qualifying work and documentation. Other terms differ. The actual policy and insurer determination control.
Avoid unsafe spaces and arrange appropriate temporary protection for active entry. Keep records of relevant work without climbing onto the roof.
Repairability, damage extent and concealed conditions determine roofing work.
Reporting requirements and deadlines vary. The insurer supplies the coverage decision and required claim process.
Tell us where the property is and what you've noticed. A free roof inspection helps establish the next useful step for your storm-damaged roof.